
The Auction Strategy That Saved Thousands on a Mortdale/Penshurst Walk-Up
A next-home buyer had just sold and moved into a rental, with their heart set on exactly two suburbs. What followed was a 12-week search, 13 off-market options, and an auction won through pure strategy rather than deep pockets.
The Brief
My client had recently sold their home and was renting while they looked for their next one. They were only interested in Mortdale or Penshurst, no other suburbs would do, and within that, we also had to rule out the pocket near the Mortdale RSL redevelopment. That's an extremely tight geographic brief before we'd even started.
They wanted a good-sized two-bedroom apartment, specifically:
• A three- or four-storey red or orange brick walk-up, nothing built post-2000, and nothing with a lift
• A mid-level floor, not ground, not top
• Two genuinely proper-sized bedrooms, not a second bedroom that was really just a study
• A good-sized kitchen, and one bathroom was fine
• Garage parking, ideally with power, so it could double as storage
• Internal laundry, non-negotiable
• North-facing living space, non-negotiable
• No west-facing bedrooms
They were happy to live with a slightly dated kitchen or bathroom, but specifically didn't want one that had been renovated cheaply just to flip the property for sale. On the strata side, they wanted a building that was predominantly owner-occupied, with a genuinely proactive maintenance scheme and owners willing to fund future works rather than relying on special levies.
The Search
With only one and a half suburbs to search in, and a genuine need for both north-facing living and a mid-floor position, the pool of eligible apartments was small from the start. Over 12 weeks, I found 13 off-market options worth considering. One got serious attention, but we ultimately parked it: the outlook from the balcony looked straight into the neighbouring apartment block, which wasn't the outcome we wanted for our client.
The Property
The apartment we secured came to my attention pre-market. In the same block, a different agent was taking a ground-floor unit to auction, a property my client wasn't interested in, but one that mattered enormously to our strategy. That ground-floor unit had a kitchen and bathroom renovation completed within the last five years, and a renovation like that typically adds a minimum of $50,000 in value. That meant whatever it sold for would effectively set a price ceiling, and we planned to come in at least $50,000 under it for the apartment we wanted.
That ground-floor auction turned out to be a very strong one. Against a price guide of $850,000, it sold for $973,000, with nine registered bidders, though only two of them seriously fought it out above $900,000.
Given that result, the agent and owner of the apartment we wanted weren't willing to entertain offers before auction. They simply didn't know what a realistic price looked like anymore. Normally I try to avoid taking full-service clients to auction. This time, our hands were tied.
Heading Into Auction, Armed With Information
I went into this auction knowing far more than most bidders in the room:
• The underbidder from the ground-floor auction two weeks earlier wasn't interested in this apartment as she only wanted level access
• Three other bidders from that same auction had already bought elsewhere and wouldn't be back
• The agent was expecting five registered bidders, including us
• The agent believed the reserve was realistic, sitting within the $800,000–$850,000 guide, and that the property would sell on the day
• I knew the auctioneer, and how he typically ran an auction
Auctions aren't just about who has the deepest pockets. They're about strategy. If someone else is genuinely willing to pay more than your client, no strategy changes that. But if you're going to be the buyer regardless, there is absolutely a strategy to paying the lowest possible price for it.
The Auction Strategy
Before the auction started, I identified the other four registered bidders and made sure I was positioned with a clear line of sight to all of them, so I could read their body language throughout.
The auctioneer called for an opening bid several times and was met with silence. I never want a vendor bid to be made. Once that happens, the auctioneer effectively controls the room, and that's not in a buyer's favour. After a long silence, I opened the bidding myself at $800,000.
A few small bids went back and forth between us and two other parties. Then I stopped bidding altogether, without giving away anything through body language, and let the two remaining bidders who hadn't yet participated come in and do their thing.
Once it was clear it had come down to the last bidder standing, I came back in with small, incremental bids and secured the property well under my client's maximum.
The Outcome
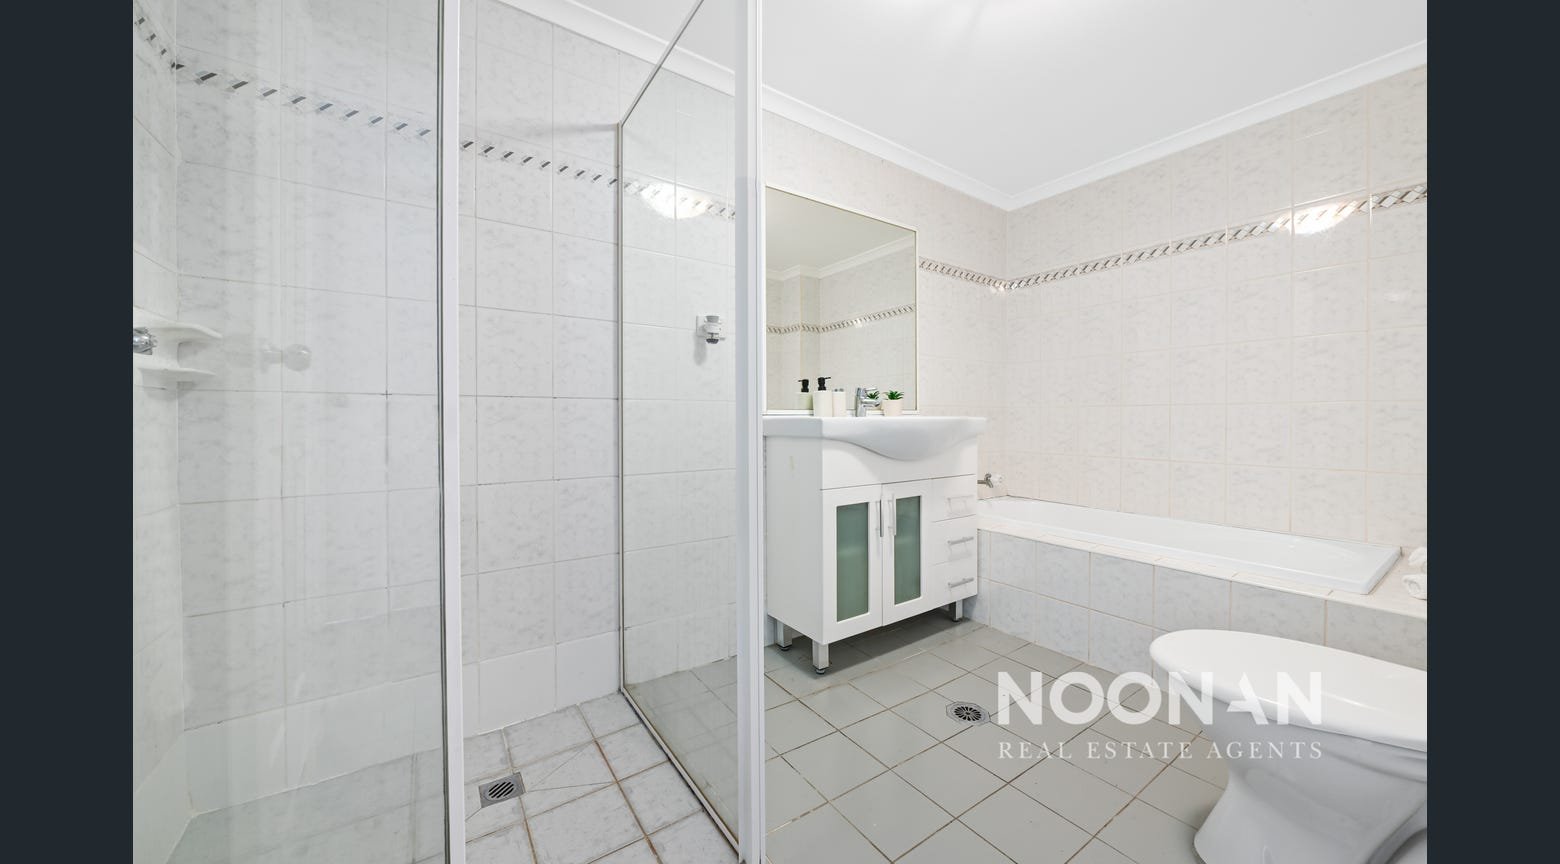
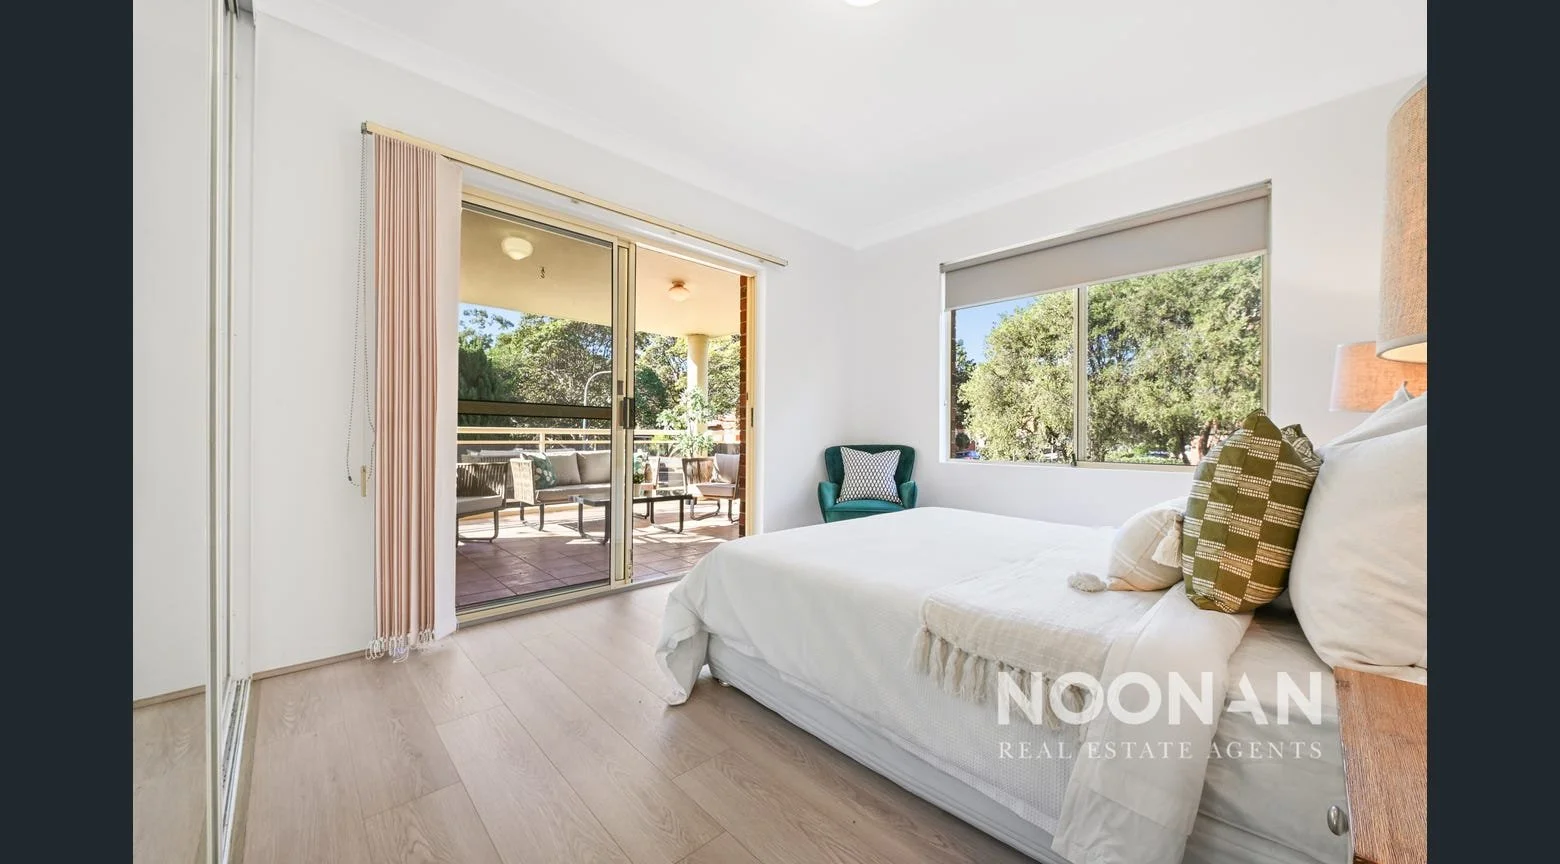
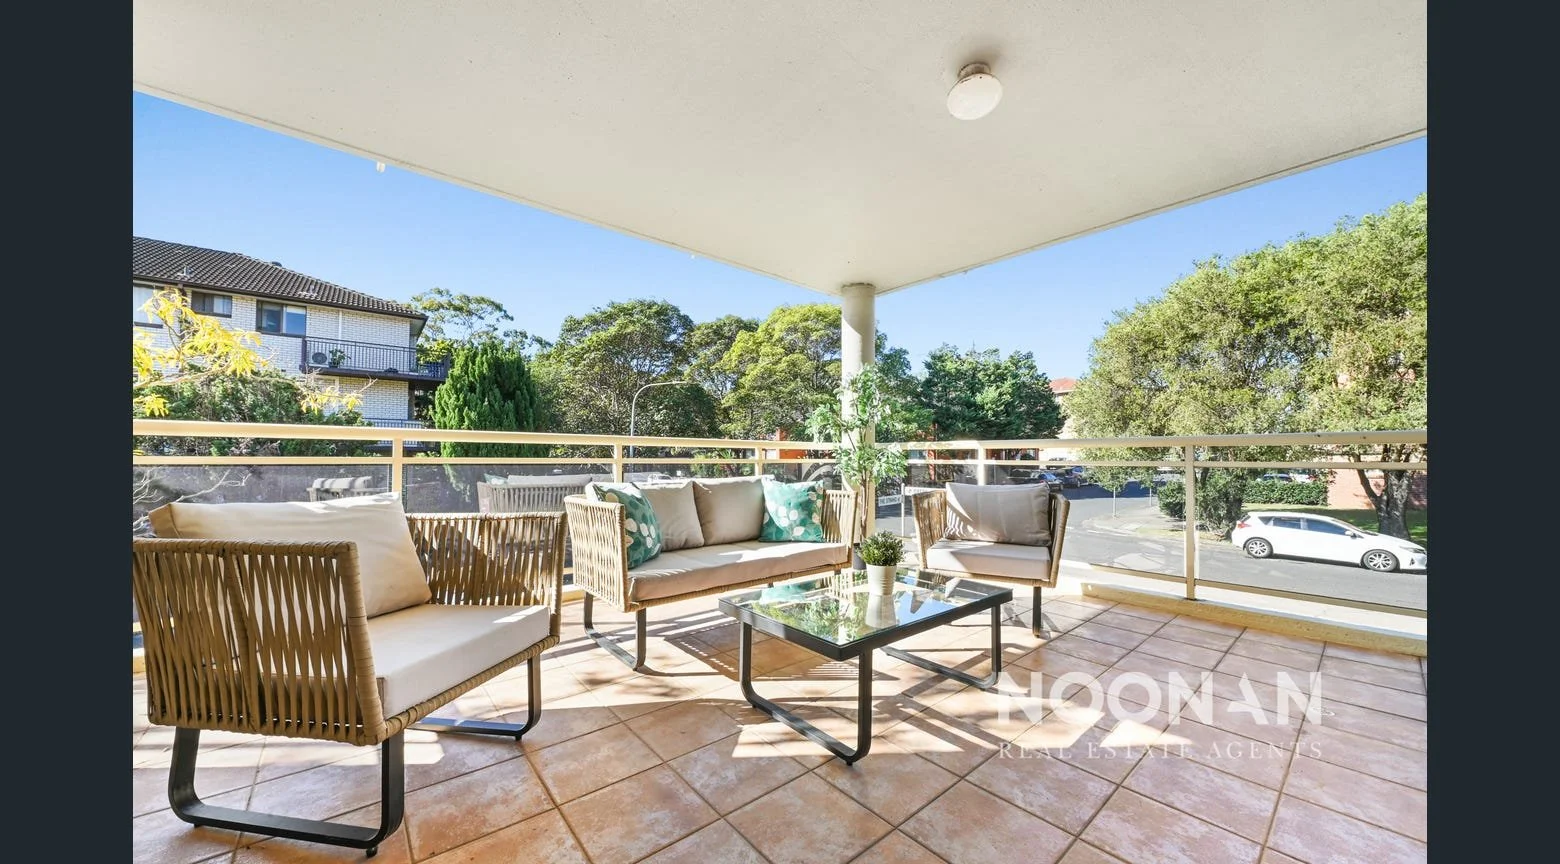
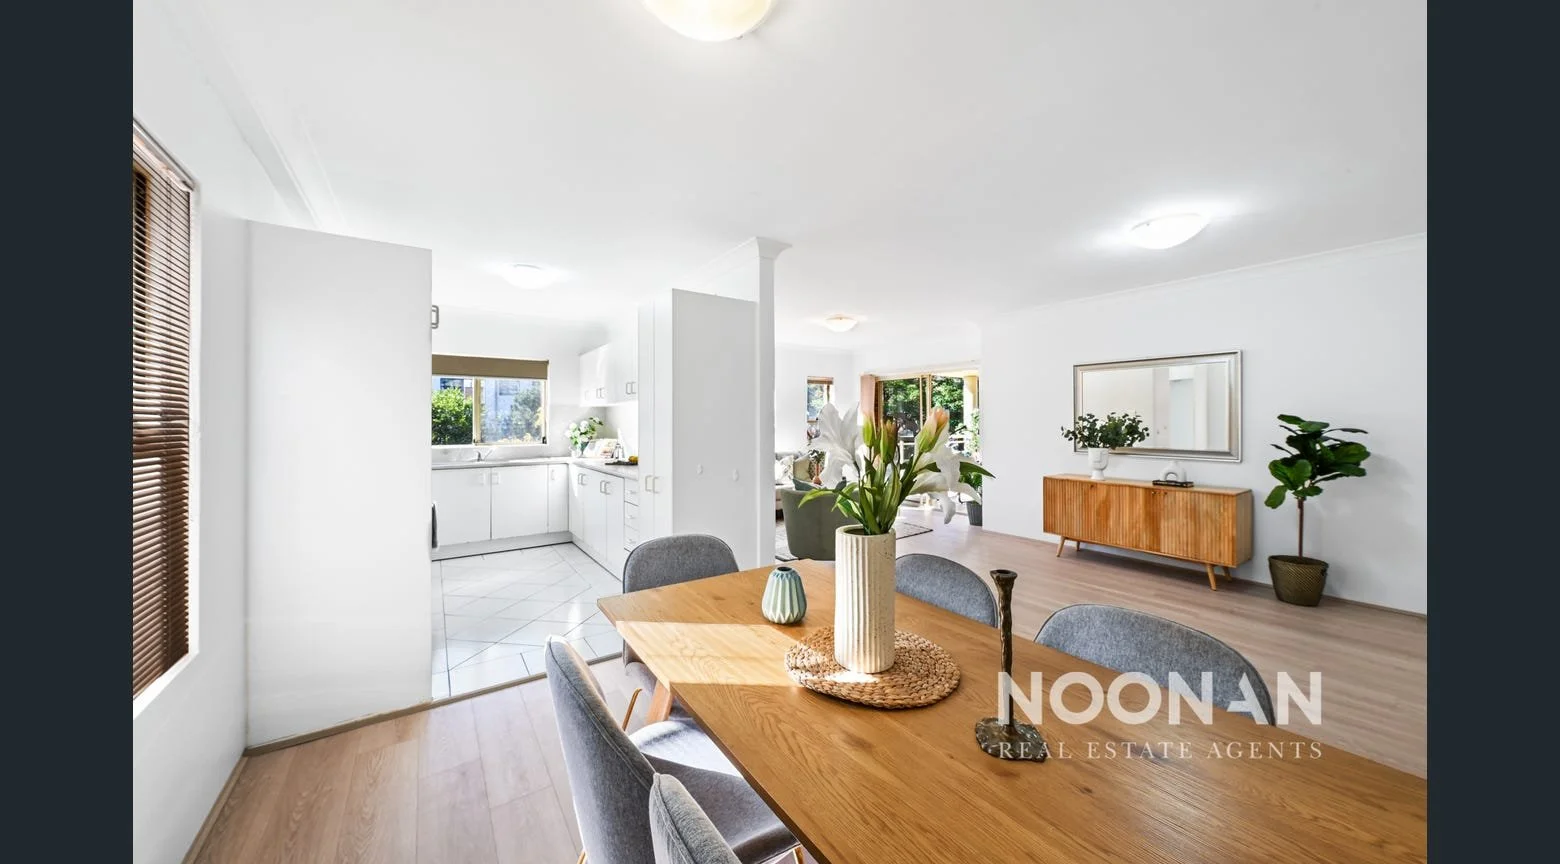
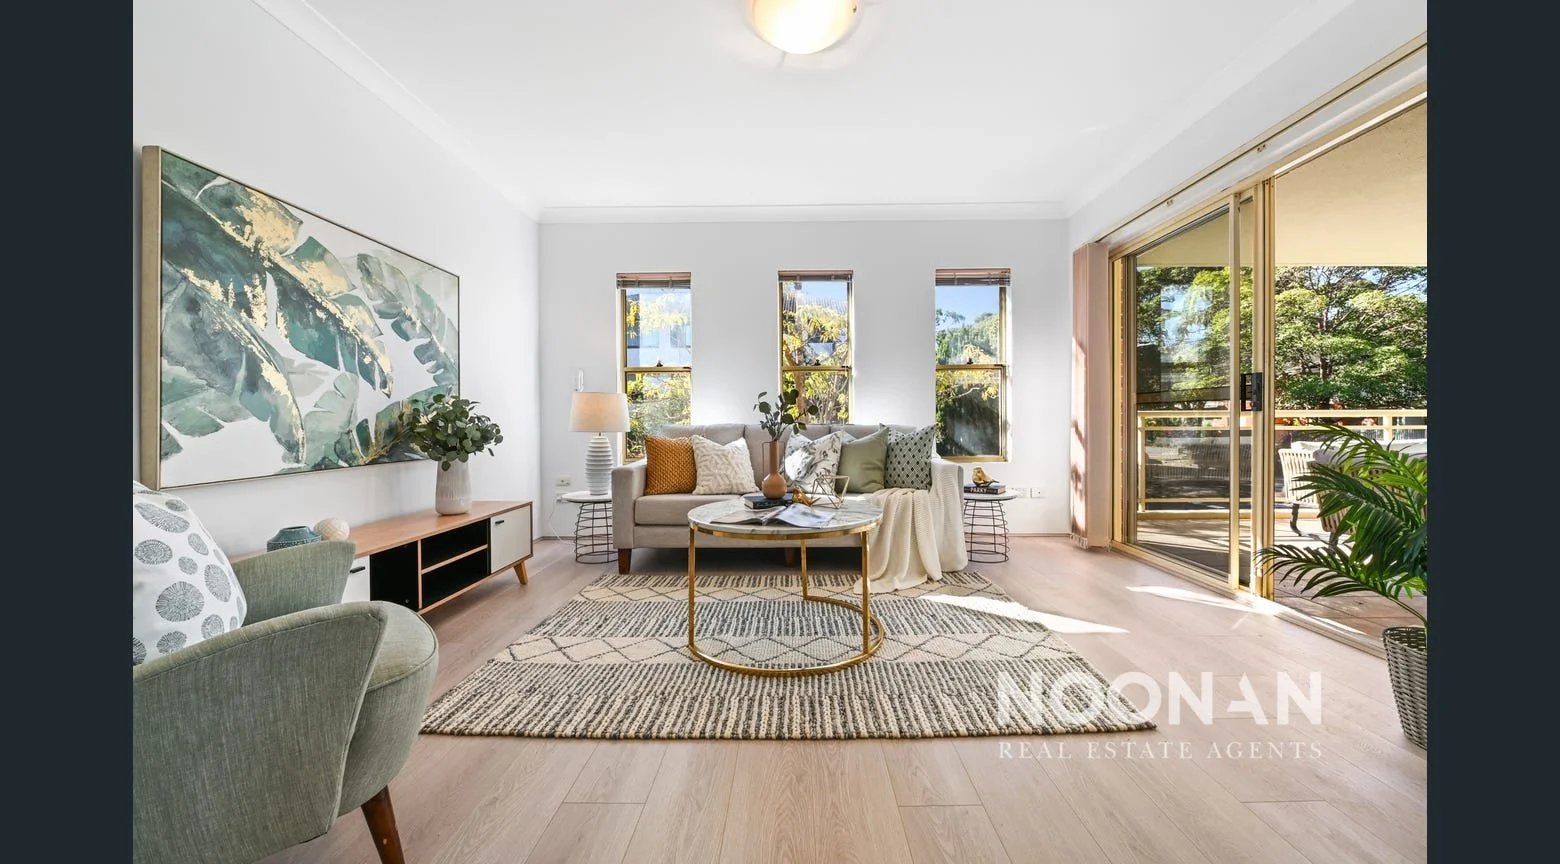
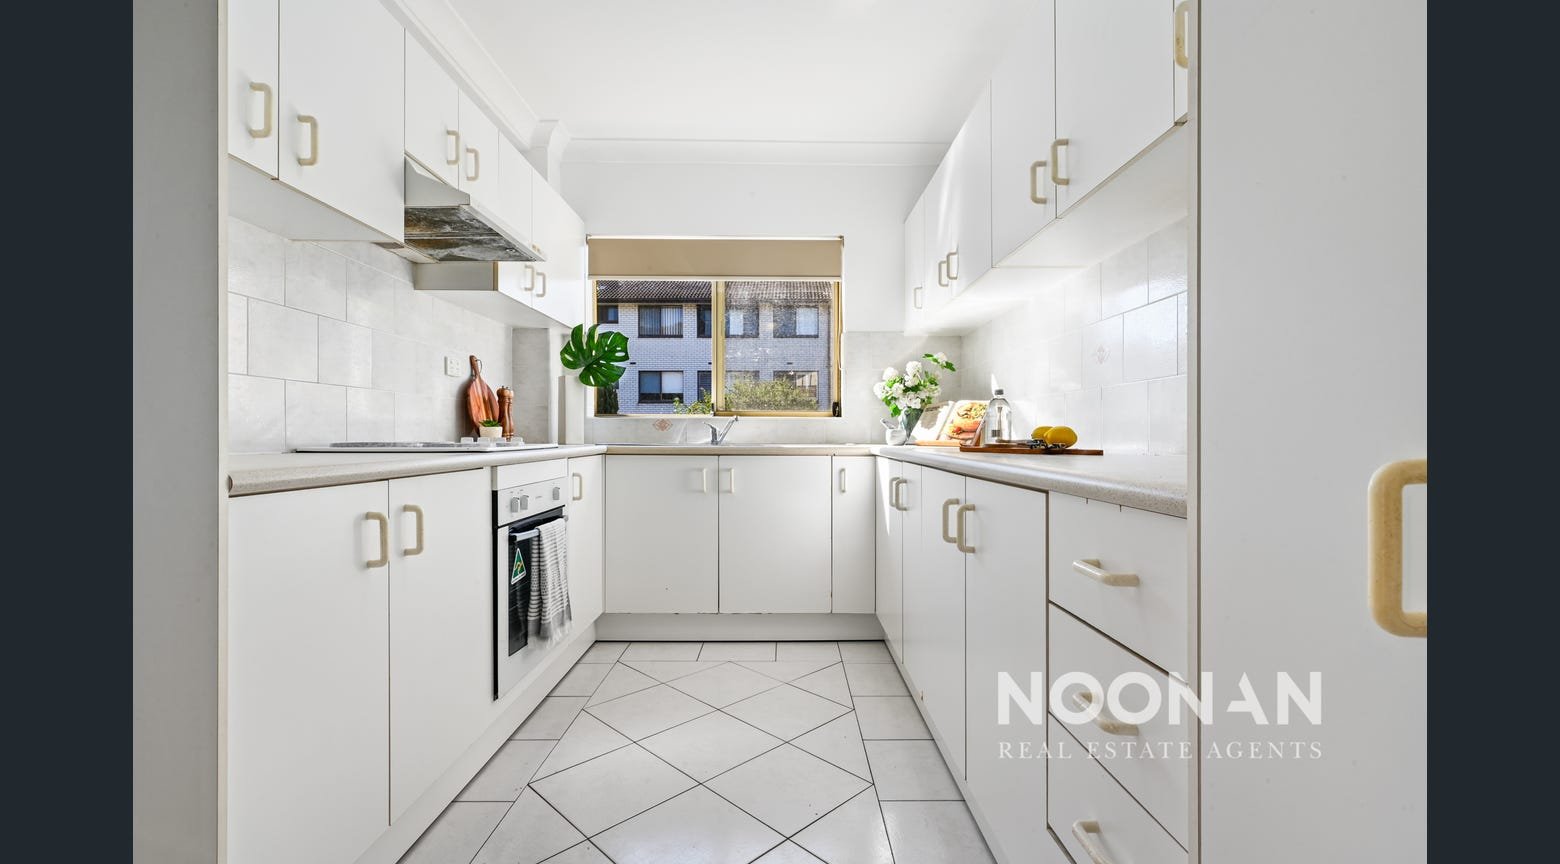
We secured a north-facing, mid-floor apartment matching every one of our client's non-negotiables, in a market where the block next door had just delivered a red-hot $973,000 sale.
We came in circa $100,000 under the sale from two weeks earlier.
Rather than opening at the client's ceiling to guarantee the win, we let the room show its hand first, then closed it out with the smallest bids we could get away with.
Why Preparation Pays Off
I always tell clients the same thing when we're setting an auction limit: I will only spend their money the way I would spend my own. That doesn't mean opening at their maximum just to be certain of the win, it means walking in with enough information to know exactly when to bid, when to sit back, and when a small increment is worth more than a bold one. In a slow-moving auction with small increments, the winning move wasn't a knockout bid, it was patience, and letting the other bidder tire themselves out.
